
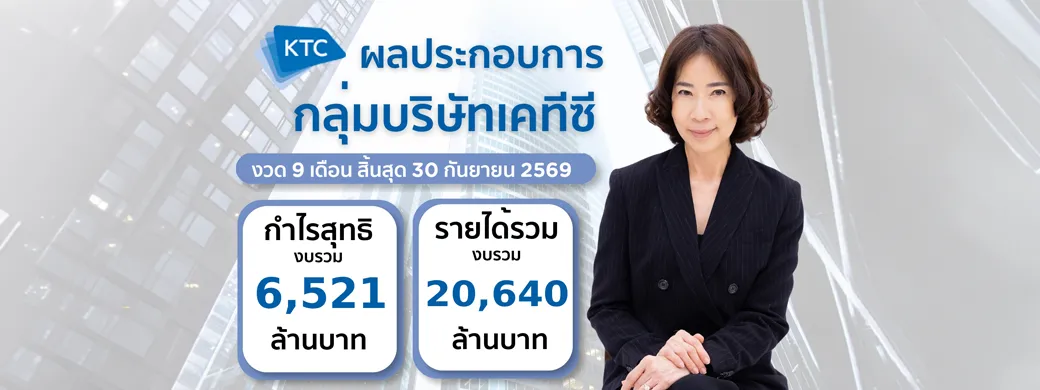
KTC Group continued to deliver profit growth in the third quarter of 2026 despite an uneven economic recovery and fragile consumer purchasing power that continued to weigh on economic activity across many parts of the country. The Group reported net profit of Baht 2,125 million, representing year-on-year growth of 8.9%. Credit card spending volume for the first nine months of 2026 increased by 4.7%, reflecting the strength of its business model, portfolio quality, and effective risk management practices.
Mrs. Pittaya Vorapanyasakul, President & Chief Executive Officer of Krungthai Card Public Company Limited (KTC), said “Industry growth as of the end of the third quarter of 2026 continued to face pressure from Thailand’s subdued economic expansion and uneven recovery. Household purchasing power is constrained by elevated debt levels and cost-of-living pressures, leading consumers to be more cautious in spending and new borrowing. At the same time, the repayment capacity of certain customer segments remains fragile, prompting lenders across the industry to continue adopting prudent lending practices, with a focus on credit quality and risk management.
Despite the industry's gradual expansion, KTC continued to maintain a strong market position across all of its core products. During the first eight months of 2026, the Company maintained its personal loan receivables market share at 4.2%, broadly in line with the same period last year. Meanwhile, its credit card receivables market share increased from 14.5% to 14.6%, while its share of credit card spending volume rose from 13.1% to 13.3%, respectively, compared with the same period last year.
“KTC Group reported net profit of Baht 2,125 million for the third quarter and Baht 6,521 million for the first nine months of 2026. These results reflect the strength of our business model, which prioritizes quality growth by balancing business expansion with prudent risk management while maintaining asset quality at an appropriate level. Economic challenges need not be a barrier to growth when an organization maintains strong disciplined risk management and a deep understanding of consumer behavior. Our continued earnings growth reflects the strength of our membership base, portfolio quality, and our ability to adapt to evolving market conditions.”
“To further strengthen its capabilities in offering insurance protection products through both offline and online channels, while meeting customer needs and maintaining competitive offerings, KTC is preparing the required documentation to register its electronic insurance brokerage business activities which will enable KTC to offer insurance policies through electronic channels. Approval from the relevant regulatory authority is expected within the fourth quarter of 2026. In addition, on August 25, 2026, KTC acquired ordinary shares in Win Performance Co., Ltd., its debt collection service partner, making it a subsidiary of the Company and member of the Krungthai Bank Public Company Limited’s financial group. The acquisition supports KTC's strategy to enhance operating cost efficiency and generate revenue through future collaboration between KTC and companies within the Bank’s financial business Group.”
As of September 30, 2026, KTC Group's total membership base stood at 3,869,210 accounts. Total loans receivable and accrued interest amounted to Baht 107,717 million, representing growth of 0.8%, while the Group's non-performing loan (NPL) ratio remained at 1.92%, reflecting satisfactory asset quality.
Credit card members totaled 3,158,768 cards, an increase of 8.8%. Credit card receivables and accrued interest reached Baht 70,055 million, up 0.9%, while credit card spending volume for the first nine months of 2026 rose 4.7% to Baht 229,884 million. The credit card NPL ratio stood at 1.21%.
Personal loan members totaled 710,442 accounts, up 0.8%. Personal loan receivables and accrued interest reached Baht 36,533 million, up 1.9%, while the personal loan NPL ratio stood at 2.65%.
The leasing receivables portfolio totaled Baht 1,130 million, down 30.6% from a year earlier, reflecting the Company's policy to discontinue new lending under this category since August 2023 and focus on debt collection and the management of the existing portfolio.
For the third quarter of 2026, KTC Group reported total revenue of Baht 6,917 million, up slightly by 0.2% year on year, supported by growth in both interest income and fee income of 1.1% and 0.4%, respectively. Total expenses declined 2.0% to Baht 4,256 million, primarily reflecting a 16.4% reduction in finance costs resulting from efficient funding cost management, together with a 1.2% decrease in operating expenses.
As a result, the Group's cost-to-income ratio improved to 35.3% in the third quarter of 2026, compared with 35.8% in the same period last year. Expected credit losses for the quarter amounted to Baht 1,457 million, increasing 0.9% year on year, while the nine-month figure totaled Baht 4,155 million, decreased by 8.9%.
KTC maintained a strong liquidity position with available short-term credit facilities of Baht 19,880 million. Long-term borrowings and debentures due during the remainder of the fourth quarter of 2026 totaled Baht 9,130 million, reflecting strong liquidity and adequate funding capacity to meet its near-term debt obligations, while indicates very low default risk.
Total expenses declined 2.0% to Baht 4,256 million, mainly due to a 16.4% reduction in finance costs, reflecting market interest rate trends and lower funding costs on new borrowings, coupled with prudent funding management aligned with loan portfolio growth.
Mrs. Pittaya added, “KTC remains committed to continuously enhancing its products, services, and member benefits through technology-driven systems that enable more precise and comprehensive personalized offerings. These efforts are designed to address the evolving needs of our members while ensuring our strategies remain aligned with an increasingly dynamic business environment. At the same time, the Group continues to enhance operational efficiency through its transformation into a fully digital organization, delivering an improved member experience while maintaining organizational agility to respond to competitive challenges. We also remain committed to fostering long-term customer relationships.”
KTC has continued to support debt relief initiatives in line with the Bank of Thailand's guidelines. In June 2026, the Bank of Thailand announced new service fee standards for financial institutions, including a reduction in the credit card cash advance fee from 3.0% to 2.5% of the withdrawal amount, effective 1 July, 2026.
The Company has also entered into a cooperation agreement with Sukhumvit Asset Management Co., Ltd. (SAM) to participate in a debt resolution program equivalent to the “Debt Clinic by SAM” Program to assist KTC's retail debtors in systematically addressing household debt, effective from 1 September, 2026 onwards/ The Company expects that the program, together with its existing customer assistance measures, will not have a material impact on the Group's overall operating performance.
For more information on KTC's customer assistance measures, please visit KTC Debtor Assistance Measures.